

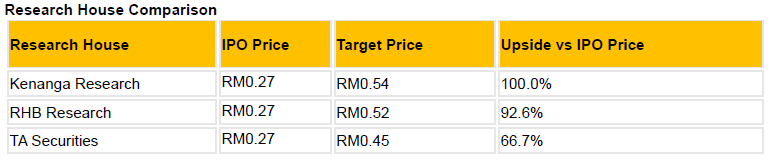
Semiconductor-linked industrial solutions provider EcoSys (Malaysia) Berhad is drawing positive attention from research houses ahead of its ACE Market debut on 14 October 2026, with target prices ranging from RM0.45 to RM0.54, representing potential upside of between 66.7% and 100% from its IPO price of RM0.27 per share.
The company plans to raise RM39.34 million through the issuance of 145.7 million new shares, with the proceeds earmarked for expanding its abatement systems business, strengthening operational capabilities, growing its presence in India and repaying bank borrowings.
RHB Research assigned a target price of RM0.52, representing 92.6% upside potential. The firm believes EcoSys stands to benefit from increasing demand for environmental compliance solutions as semiconductor manufacturers continue expanding capacity while facing stricter sustainability requirements.
Three Research Houses Positive on EcoSys
Among the IPO research reports reviewed, Kenanga Research is the most optimistic on the stock, assigning a target price of RM0.54, implying 100% upside from the IPO price. The research house highlighted EcoSys’ exposure to long-term growth trends in both the semiconductor and solar photovoltaic industries, particularly in India, where manufacturing localisation initiatives are accelerating.
Meanwhile, TA Securities valued the company at RM0.45 per share, implying 66.7% upside from the IPO price. The research house cited EcoSys’ proprietary technology, established customer relationships and experienced management team as key investment strengths.
Positioned Within the Semiconductor Supply Chain
EcoSys operates two core business segments:
– Ultra-high purity (UHP) fabrication of precision engineering components and sub-assembly modules
– Design, assembly and maintenance of abatement systems used to treat harmful by-products generated during semiconductor and solar manufacturing processes
The group supplies customers involved in semiconductor equipment manufacturing, solar photovoltaic production and industrial gas applications.
According to TA Securities, EcoSys has built a competitive position through the development of proprietary abatement technologies supported by in-house research and development capabilities. The company also maintains industry certifications, including SEMI compliance standards and ISO-certified manufacturing facilities, positioning it to serve multinational customers operating within highly regulated industries.
Its customer relationships have also proven resilient, with certain clients having engaged the company for well over a decade, providing recurring business opportunities and long-term earnings visibility.
India Emerging as a Key Growth Engine
A common theme across all three research reports is EcoSys’ increasing exposure to India.
India contributed approximately 35.1% of the group’s FY2025 revenue, making it one of EcoSys’ most important overseas markets. The company intends to establish a dedicated sales and service centre in India using part of its IPO proceeds to deepen customer engagement and support future business expansion.
Research houses believe India could become a significant catalyst as the country aggressively expands its semiconductor and solar manufacturing industries.
Kenanga Research noted that India is targeting substantial growth in domestic solar manufacturing capacity over the coming years, creating long-term demand for abatement systems and related environmental solutions.
Similarly, RHB highlighted that EcoSys has already secured several new customers in India for its abatement business and is actively pursuing additional opportunities as industrial investment accelerates.
Abatement Segment Seen as Main Earnings Driver
While EcoSys’ UHP fabrication business continues to provide a stable revenue base, the group’s proprietary abatement segment is increasingly viewed as its primary growth engine.
Abatement systems are used to remove or neutralise hazardous gases generated during semiconductor and solar panel manufacturing processes. As environmental standards become more stringent, demand for such systems is expected to rise alongside increased capacity expansion by semiconductor and solar manufacturers.
The segment has grown rapidly in recent years and now accounts for a meaningful proportion of the group’s revenue mix. Analysts generally expect the business to deliver higher margins than the group’s fabrication activities due to its proprietary technologies and intellectual property ownership.
RHB projects EcoSys to deliver healthy earnings growth over the next few years, supported by increasing demand for abatement solutions and expanding participation within the semiconductor supply chain.
Healthy Order Book Supports Outlook
EcoSys enters its ACE Market debut with an order book of approximately RM94.3 million, providing earnings visibility over the near term.
The company has also relocated to a larger facility in Simpang Ampat, Penang, enabling it to increase production capacity while supporting future expansion plans.
IPO proceeds will additionally be directed towards:
– Expansion of the abatement business
– Procurement of machinery and equipment
– Workforce expansion
– Establishment of a sales and service centre in India
– Repayment of bank borrowings
These initiatives are expected to strengthen the group’s ability to capture opportunities arising from continued growth in the semiconductor and solar manufacturing sectors.
Outlook
While analysts acknowledge risks such as semiconductor industry cyclicality, customer concentration and foreign exchange fluctuations, the overall view remains positive.
The combination of proprietary technology, expanding exposure to India, growing demand for environmental compliance solutions and a healthy order book has led research houses to adopt a constructive stance on the stock.
With target prices ranging from RM0.45 to RM0.54, EcoSys is shaping up as one of the more closely watched semiconductor-related IPOs ahead of its ACE Market listing on 14 October 2026.

