


KUALA LUMPUR, 2 November 2026 – RHB Research has assigned a fair value of RM0.84 to Betamek Berhad (Bursa: 0263), representing a potential upside of 29% from its reference share price of RM0.66, supported by the Group’s diversification into electronics manufacturing services (EMS), improving profit margins and attractive dividend yields.
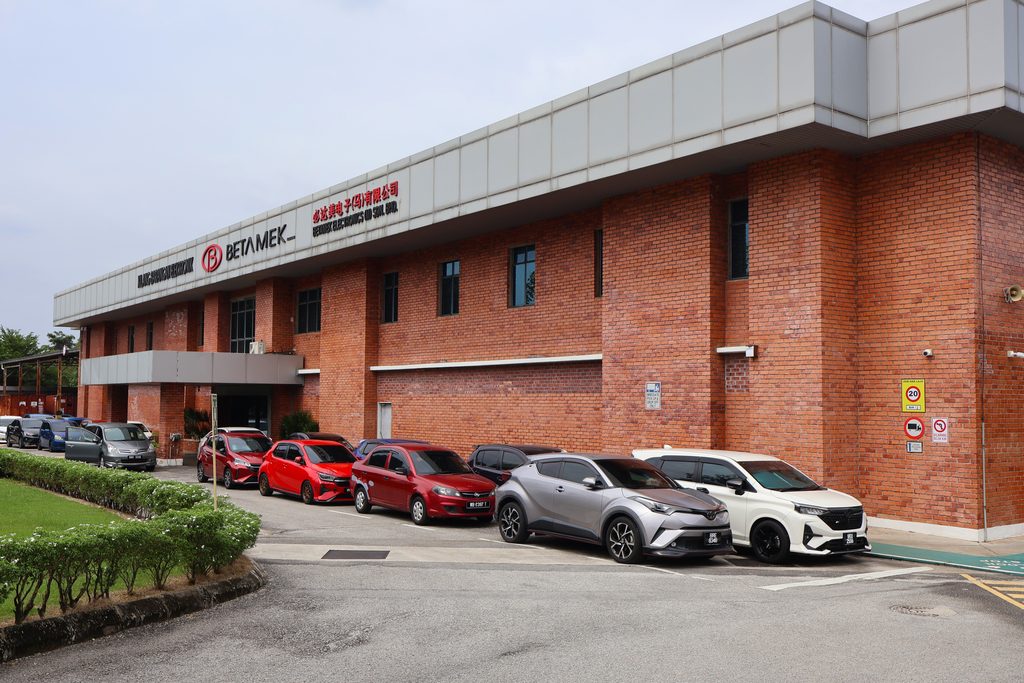
Betamek Berhad
In its latest research report, RHB Research highlighted Betamek’s growth potential, projecting a five-year earnings compound annual growth rate (CAGR) of 21%, driven by customer diversification, higher electronic content in vehicles and expanding export opportunities.
A key growth driver is Betamek Sanshin Sdn Bhd (BSSB), which has enabled the Group to reduce its reliance on Perodua while strengthening its presence in overseas markets.
Perodua’s revenue contribution declined to 82% in FY2026 from 93% in FY2025, while export sales increased to 12% of Group revenue from 2% previously. Hong Kong accounted for approximately 11% of revenue in FY2026.
RHB Research noted that BSSB’s current capacity utilisation of approximately 40% provides significant room for expansion, with potential new customers and consumer electronics contracts expected to support growth from FY2028 onwards.
Meanwhile, Betamek has expanded its product portfolio by 26 additional components since its initial public offering, positioning the Group to benefit from increasing electronic content in newer vehicle models.
The research house also expects a stronger ringgit to support profitability, as approximately 80% of Betamek’s costs are denominated in foreign currencies. Every 1% appreciation in the ringgit against the US dollar could increase annual earnings by 1% to 2%, assuming fully unhedged exposure.
RHB Research forecasts revenue to increase from RM276 million in FY2026 to RM348 million in FY2028, with recurring net profit rising from RM33 million to RM42 million.
Additionally, Betamek’s guided dividend payout ratio of 70% to 80% for FY2027–FY2028 is expected to translate into dividend yields of approximately 8% to 10%.
RHB Research derived its RM0.84 fair value based on nine times FY2028 forecast earnings, while highlighting slower-than-expected contract wins, foreign exchange volatility and rising raw material prices as key risks.

